Lease vs Buy: The Honest Comparison
What each option really promises, what it costs, and the four questions that pick the right one for you.
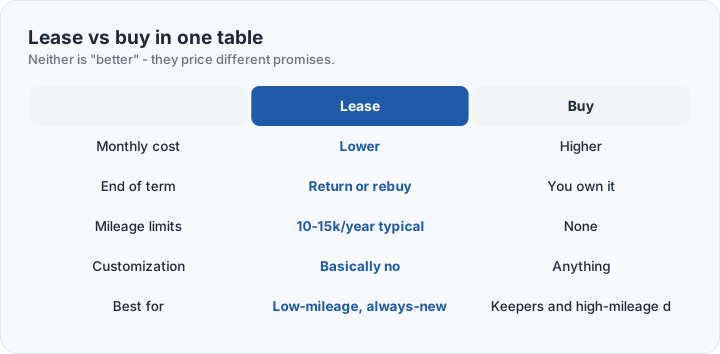
Strip the marketing and a lease is a promise: "pay for the part of the car you use, return the rest." A purchase is the opposite promise: "pay for all of it, keep all of it." Neither is a scam; they price different relationships with the same machine.
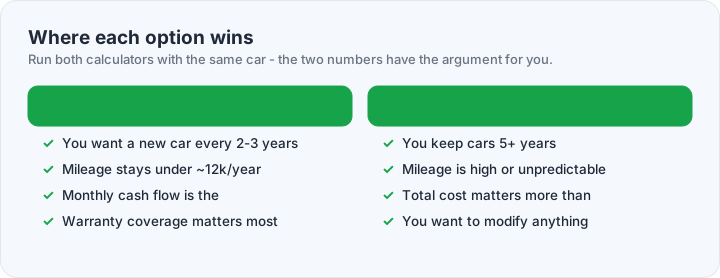
The lease wins on monthly arithmetic — you finance only the depreciation years, so the payment is lower for the same car. It wins again on turn-key simplicity: new car every three years, warranty coverage the whole time, no selling ceremony. It loses on total cost of ownership (a perpetual lease never stops charging depreciation), on mileage freedom, and on modification rights — which are effectively zero.
Buying wins the long game: payments end, equity accumulates, and cost-per-year collapses for anyone who keeps a car past year five or six. It loses the short game — higher payments, and years three through five of a new car's life are the expensive maintenance frontier.
The four questions that decide it: How many miles do you actually drive (leases punish commuters)? How long do you keep cars (keepers should buy)? Does monthly cash flow bind harder than total cost (leases ease cash flow, buy wins total)? Do you treat cars as appliances (lease) or as assets (buy)? Run both calculators — the lease tool and the payment tool — with the same car and let the two numbers have the argument.
Frequently asked questions
Is it cheaper to lease or buy?
Per month, lease. Per year of ownership past year five, buy — a purchased car's payment ends while a lease cycle never does.
What happens at the end of a lease?
Return the car (inspection fees apply for excess wear/miles), or buy it at the residual price stated in your contract — sometimes a bargain if used values ran hot.
Can I negotiate a lease?
Yes — the cap cost is a car price (negotiable), and the money factor is an interest rate in disguise (check it against our rates page × 2,400).
What fees should I expect at lease signing?
Typically an acquisition fee (the bank, $600-1,000), documentation fees, first payment, and registration — plus whatever down payment you choose. The calculator fees box captures the rolled-in ones.
Is leasing worse for my credit?
No — a lease is an installment account like a loan. On-time lease payments build credit the same way; the difference is what you own at the end.
What mileage tier should I choose?
12,000 miles/year is the common middle. Estimate your real driving and add 10% — extra miles bought up front cost less than overage charges at turn-in.
What happens to my lease if the car is totaled?
Insurance pays the leasing company the actual value, and gap coverage (usually bundled into lease contracts) clears any remaining balance. Your drive-off money is the exposed part — one more reason leases favor low down payments.
Can I buy my lease out early?
Any time — the purchase price is the residual plus the remaining payments (per most contracts). If the used market values your car above that number, buying out and keeping (or reselling) can be the best of both worlds.