Car Loan Payoff Calculator
Add extra to your monthly payment and see the payoff date move and the interest die — computed from your actual remaining balance.
Check your loan agreement for prepayment penalties — most US auto loans have none, but confirm before wiring extra.
Early payoff is the rare financial move that is exactly as boring as it sounds: every extra dollar kills a slice of future interest permanently. The mechanics are worth understanding, though, because lenders do not always apply extras the way you intend.
The critical detail is the principal-only instruction. An extra payment applied to "next payment due" often just pre-records next month — advancing the calendar without touching interest. You want it applied to principal, every time, in writing if the lender's app makes it hard. The savings on this page assume that is what happens.
One honest caveat about opportunity cost: if your APR is 3.9%, extra payments earn you a guaranteed 3.9% — solid, but if you carry credit card debt at 24%, that is where every spare dollar belongs first. Paying off a 6.5% car early is a moderate, guaranteed return; it is a good default, not a law.
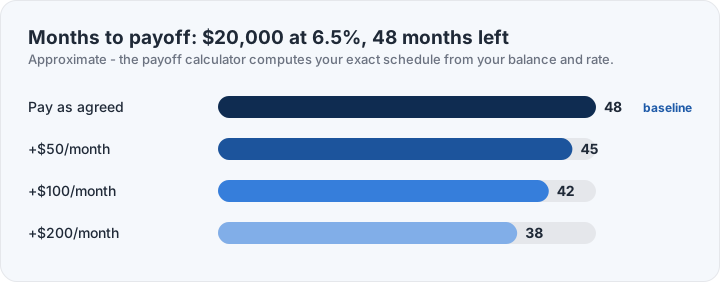
The pattern the chart shows is real and worth internalizing: extras cut months roughly linearly but cut interest front-loaded — the earlier in the loan you start, the more each extra dollar saves. The calculator computes your exact schedule from your balance and rate.
Frequently asked questions
Is it worth paying off a car loan early?
If the APR is above roughly 5%, early payoff is a solid guaranteed return. Below that, weigh it against other uses for the money — and check for prepayment penalties first.
How do I make sure extra payments go to principal?
Use the lender's principal-only option and keep the confirmation. If paying by check, write "principal payment" on the memo line.
Does paying off a car loan early hurt my credit?
Temporary and minor: the loan closes, average account age dips slightly. The score typically recovers within months — the interest savings are permanent.
Should I invest instead of prepaying a 4% loan?
A fair argument: the market has historically returned more than 4%, though not guaranteed. Prepaying a 4% loan is a guaranteed 4% — the right answer depends on your other debts and risk tolerance, not math alone.
What is a payoff quote vs my balance?
The payoff includes accrued interest since your last payment — typically a bit higher than the statement balance. Refinance offers need the payoff figure, so request it before comparing.
Does my extra payment automatically go to principal?
Not always — some lenders apply it to the next payment or to escrow-style buckets first. After each extra payment, confirm the balance dropped by the full extra amount; if it did not, call and set a standing principal-only instruction.