Auto Refinance Calculator
Compare your current loan against a refinance offer — monthly saving, total interest saving, and whether the fees are worth it.
—
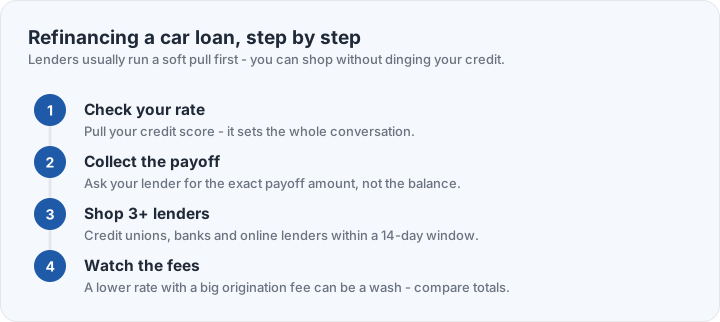
Shopping multiple lenders within a 14-day window counts as one credit inquiry with most scoring models.
Refinancing exists because your credit at loan signing is not your credit forever. The buyers who got 11% at the dealership in a rushed finance office are, two years of on-time payments later, prime candidates for something closer to 6%. The calculator above answers the only question that matters: do the new numbers beat the old ones after fees?
Watch the two numbers separately. Monthly saving is what you feel — but extending the term can lower the payment while raising total interest; the verdict line accounts for that. Total interest saving is what you keep. A refinance that does both is a slam dunk; one that lowers only the payment deserves a second look at the new term.
Timing notes that matter: most scoring models treat multiple auto-loan inquiries within 14-45 days as one, so shop hard within a window. And if your current loan is already most of the way through, refinancing can quietly restart the interest clock — the calculator models that honestly by comparing remaining months against the new term.
Frequently asked questions
When should I refinance my car loan?
Classic triggers: your credit improved since signing, rates dropped, or the original loan came from a dealer mark-up. Typically worth checking after 12+ months of on-time payments.
Does refinancing hurt my credit?
A hard inquiry and a new account — a small, temporary dip. Shopping several lenders within a 14-day window counts as one inquiry with most scoring models.
Can I refinance with the same lender?
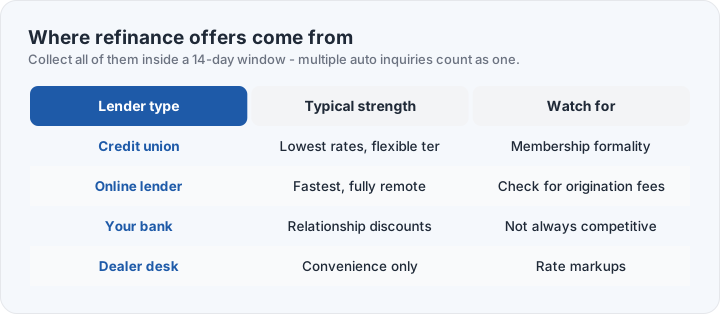
Sometimes — but the best offers usually come from comparing a credit union, a bank and an online lender against each other.
What documents do I need to refinance?
The standard set: recent pay stubs, proof of insurance, your current loan payoff quote, and the vehicle VIN and mileage. Having them ready cuts the process to a day or two for most online lenders.
Can I refinance a car with high mileage or an older model?
Lender caps on age and mileage are real — many won't refinance vehicles older than about 8-10 years or past 100-125k miles. Credit unions are usually the most flexible; online lenders publish their limits on the application page.
Why did my dealer rate differ from my bank pre-approval?
Dealer-arranged loans can include a rate markup — the lender approves you at one rate and the desk adds a margin. Your pre-approval letter is what keeps that visible and negotiable.
Can I refinance twice?
Yes — there is no legal limit, only math: each time, compare the new total cost against what is left of the old loan. People typically refinance again after another credit jump or a big rate move.